 0
 0
You got the raise. Maybe it was a promotion, a better job, or a side hustle that finally started paying. For a few weeks, it felt like breathing room.
Then, somehow, it was gone. Not stolen. Not lost. Just… absorbed. The account looks the same at the end of the month as it did before. You are earning more and you do not feel any richer.
That has a name. It is called lifestyle creep, and it is one of the most common money problems there is, because it does not feel like a problem while it is happening. It feels like a normal life.
What Is Lifestyle Creep?
Lifestyle creep is what happens when your spending quietly rises every time your income rises. Each new upgrade feels small and reasonable. Together they eat the whole raise, so your savings never actually grow.
Some people call it lifestyle inflation. The meaning is the same: yesterday’s treat becomes today’s normal, and today’s normal becomes something you cannot imagine living without.
The key word is “creep.” Nobody decides to spend every extra coin. It happens one sensible-looking choice at a time:
- A slightly nicer flat, because you can afford it now.
- Takeaway twice a week instead of once, because you are tired and you have earned it.
- A newer phone, a better car, a gym with a pool.
- A few more subscriptions that each cost “hardly anything.”
None of those are wrong on their own. The trouble is the pattern. When every raise gets turned into a new baseline, you are running faster just to stay in the same place.
Why Lifestyle Creep Happens to Almost Everyone
This is not a character flaw. It happens to careful people, too, for at least three reasons.
1. It has been a “law” for over 60 years. In 1960, the British historian C. Northcote Parkinson published a book called The Law and the Profits. In it he set out what he called his second law: “Expenditure rises to meet income.” He was mostly poking fun at governments, which always seem to find a way to spend whatever they collect. But he pointed the same finger at ordinary households. And he went a step further than most people remember: he said spending does not just rise to meet income. It tends to rise past it. That is how people on good salaries still end up in debt.
2. Your brain gets used to nice things fast. The first week in the bigger flat feels amazing. By month three, it just feels like home. Psychologists call this adaptation, and it is the engine behind what is sometimes called the hedonic treadmill, where nothing new stays new. The joy fades. The cost does not.
3. Upgrades are easy to add and hard to remove. Going up feels like a reward. Going back down feels like losing. So the direction only ever goes one way unless you choose otherwise.
The Part of Lifestyle Creep Most People Miss
Here is the detail most money articles skip. The real damage usually is not the thing you bought. It is everything the thing brings with it.
A bigger home is not one cost. It is more rent, more to heat or cool, more to clean, more furniture to fill it. A car is not one purchase. It is fuel, insurance, repairs, parking, every single month. A new gadget often comes with a plan, a case, an app, a subscription.
One-off purchases end. Recurring costs keep eating. That is why a raise can vanish even when you “didn’t really buy anything big.” You didn’t. You signed up for a dozen small things that each get fed every month.
So when you look for lifestyle creep in your own life, don’t just look at what you own. Look at what you now have to keep paying for.
Signs You Might Have Lifestyle Creep
- You earn more than you did a few years ago, but your savings are about the same.
- You can’t quite say where the extra money went.
- Your list of monthly payments is longer than it used to be.
- Things that once felt like treats now feel like basic needs.
- A surprise bill still causes panic, even on a bigger income.
- You lie awake thinking about money more, not less.
That last one matters. If a higher income has somehow made you more anxious about money, not less, you are not imagining it. More to own often means more to worry about.
How to Reverse Lifestyle Creep (Without Feeling Poor)
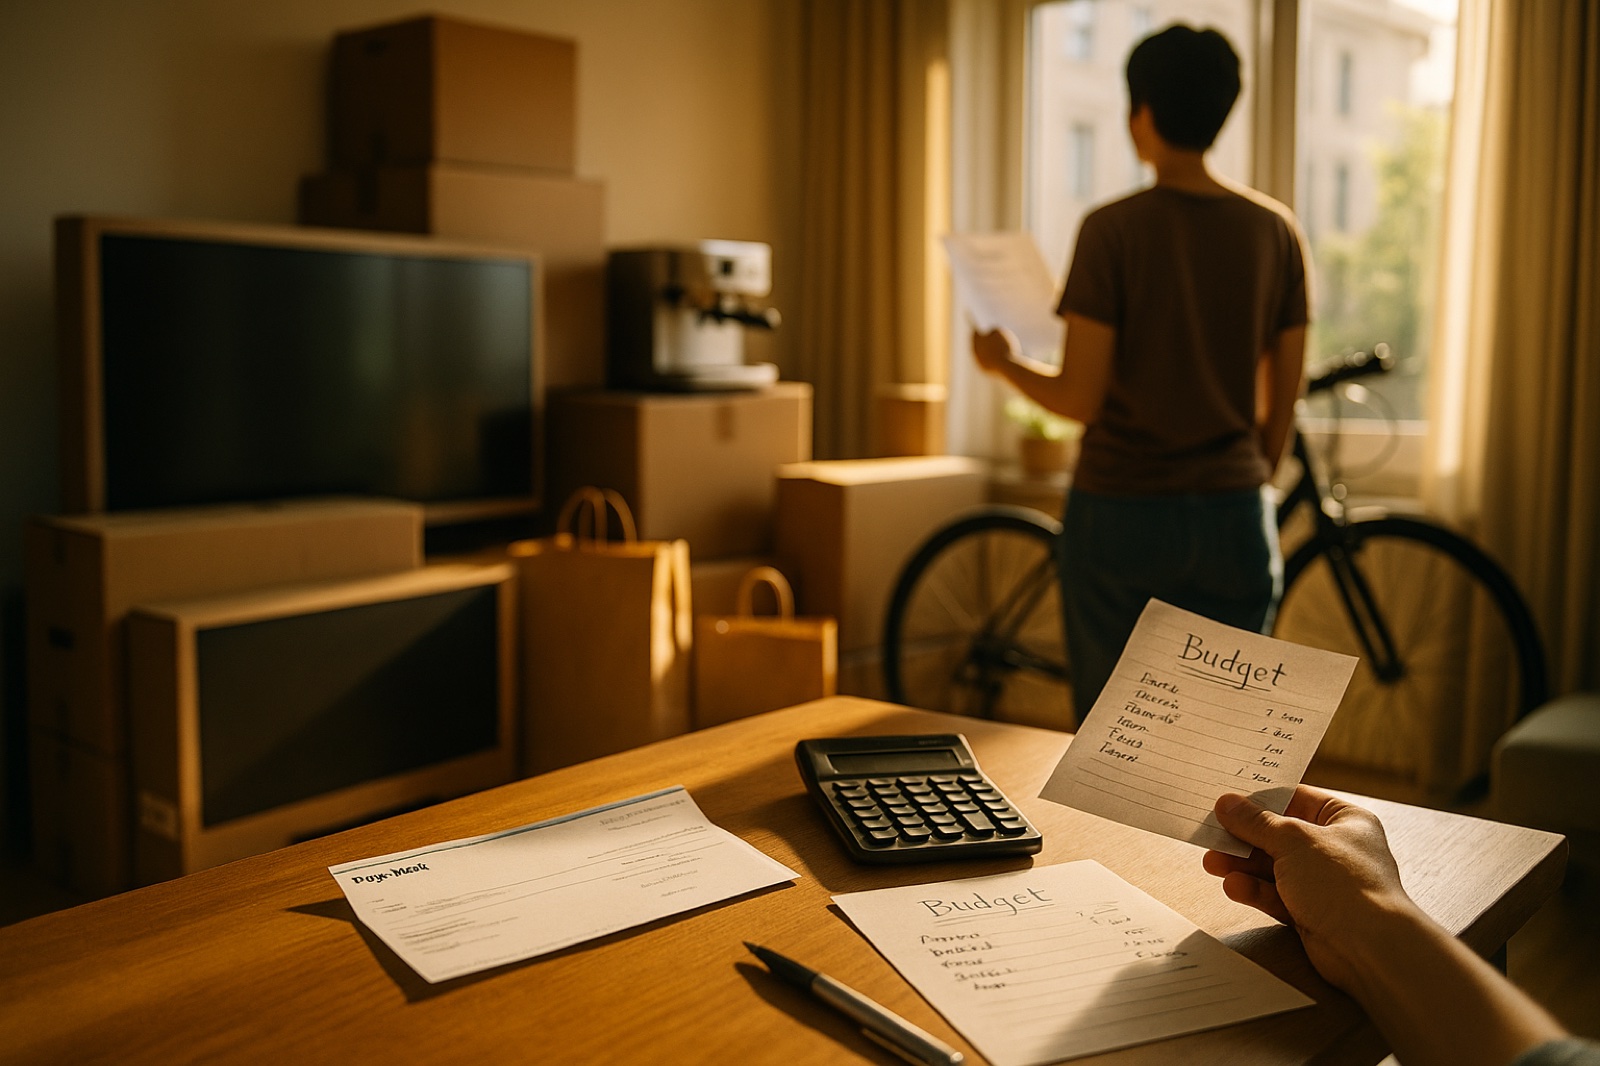
The good news is that none of this needs a financial adviser or spare cash. It needs a pen, a quiet half hour, and a little honesty.
- Write down every recurring cost. Not what you spend in a month. What you are committed to spending, every month, whether you think about it or not. This list is usually a shock.
- Circle the ones you would not sign up for today. If you would not choose it again from scratch, it is a candidate to cancel.
- Split the next raise before it arrives. Decide now that some part of any extra income goes straight to savings or paying down debt the day it lands. You cannot miss money you never got used to having.
- Use a waiting rule. For anything that would add a new monthly cost, wait 30 days. If you still want it after a month, fine. Often you won’t.
- Keep the upgrades that truly matter. Reversing lifestyle creep is not about living like a monk. It is about choosing on purpose. Keep the thing that really makes your life better. Drop the ones that just became habit.
- See it in one place. A simple, free tool like our budget calculator can show you in a few minutes how much of your income is already spoken for.
An Old Observation That Still Fits
It is a little humbling to learn that none of this is new. Long before paychecks and subscriptions, a writer in one of the Bible’s old wisdom books noticed the very same pattern:
“When goods increase, they are increased that eat them: and what good is there to the owners thereof, saving the beholding of them with their eyes?”
In that world, getting richer meant a bigger household: more servants, more workers, more guests at the table. More mouths to feed. The owner’s wealth grew, and so did the number of people living off it. What did the owner actually get? The chance to look at it.
That is lifestyle creep, described in a few lines, with the recurring costs pictured as hungry mouths. And the writer’s next line is the surprising part: “The sleep of a labouring man is sweet, whether he eat little or much: but the abundance of the rich will not suffer him to sleep.”
The ancient answer wasn’t “earn more.” It was that enough is a real place you can arrive at, and that rest is found there, not at the next pay rise. For many people, that kind of peace does not come from a bank balance at all. It comes from trusting that they are held by something bigger than their income, by God, so their stuff doesn’t have to hold them up.
Richer Is a Choice, Not a Number
You do not need a bigger raise to feel better off. You need the next raise to actually stay with you. That starts with seeing what quietly moved in when your income went up, and deciding which of those guests you really want at your table.
Do that once, honestly, and something changes. The money stops disappearing. And maybe, for the first time in a while, you sleep a little easier.
Discussion Question
What do you think is the hardest upgrade to give up once you’ve gotten used to it: housing, food, transport, or something else? Share your answer in the comments below.
Share This
“Got a raise. Somehow still broke. Turns out it has a name: lifestyle creep. This explains it better than anything I’ve read: https://bgodinspired.com/?p=116781”
“The part that got me: it’s not the stuff you buy, it’s everything the stuff makes you keep paying for. Going through my monthly costs tonight. https://bgodinspired.com/?p=116781”
“Someone described lifestyle creep thousands of years ago: more goods, more mouths to feed them, and all the owner gets is to look at it. Worth a read if your raise vanished too. https://bgodinspired.com/?p=116781”
Common Questions About Lifestyle Creep
What is lifestyle creep?
Lifestyle creep is when a person’s spending rises every time their income rises, so that a raise or promotion never leaves them with more savings. It happens through many small, reasonable-looking upgrades, such as a nicer home, more eating out, or extra subscriptions, that slowly become the new normal. It is also called lifestyle inflation.
What is an example of lifestyle creep?
A common example of lifestyle creep is getting a pay rise and then moving to a bigger flat, buying a newer car, and adding a few monthly subscriptions. Each choice seems affordable, but together the new rent, fuel, insurance, and monthly fees use up the entire raise, so savings stay the same as before the pay increase.
How do you reverse lifestyle creep?
To reverse lifestyle creep, list every recurring monthly cost, cancel the ones you would not choose again today, and decide in advance that part of any future raise goes straight to savings or debt repayment. A 30-day waiting rule for any purchase that adds a new monthly cost also helps. The goal is to keep the upgrades that truly improve life and drop the ones that only became habit.
What is Parkinson’s second law?
Parkinson’s second law states that “expenditure rises to meet income.” It was set out by British historian C. Northcote Parkinson in his 1960 book The Law and the Profits. Parkinson aimed it mainly at government spending, but applied it to households too, and argued that spending tends not only to meet income but to exceed it.
Is lifestyle creep always bad?
Lifestyle creep is not always bad. Spending more as income rises can be a healthy choice when it is deliberate, such as moving somewhere safer or buying better food. It becomes a problem when the extra spending happens without a decision, uses up the whole raise, and leaves no room for savings, emergencies, or paying down debt.